Reports create expectations
An inspection agreement, stated scope, documentation practices, and record retention can affect the questions an insurer and the business should consider.


Coverage planning for Oregon residential and commercial property inspection professionals.
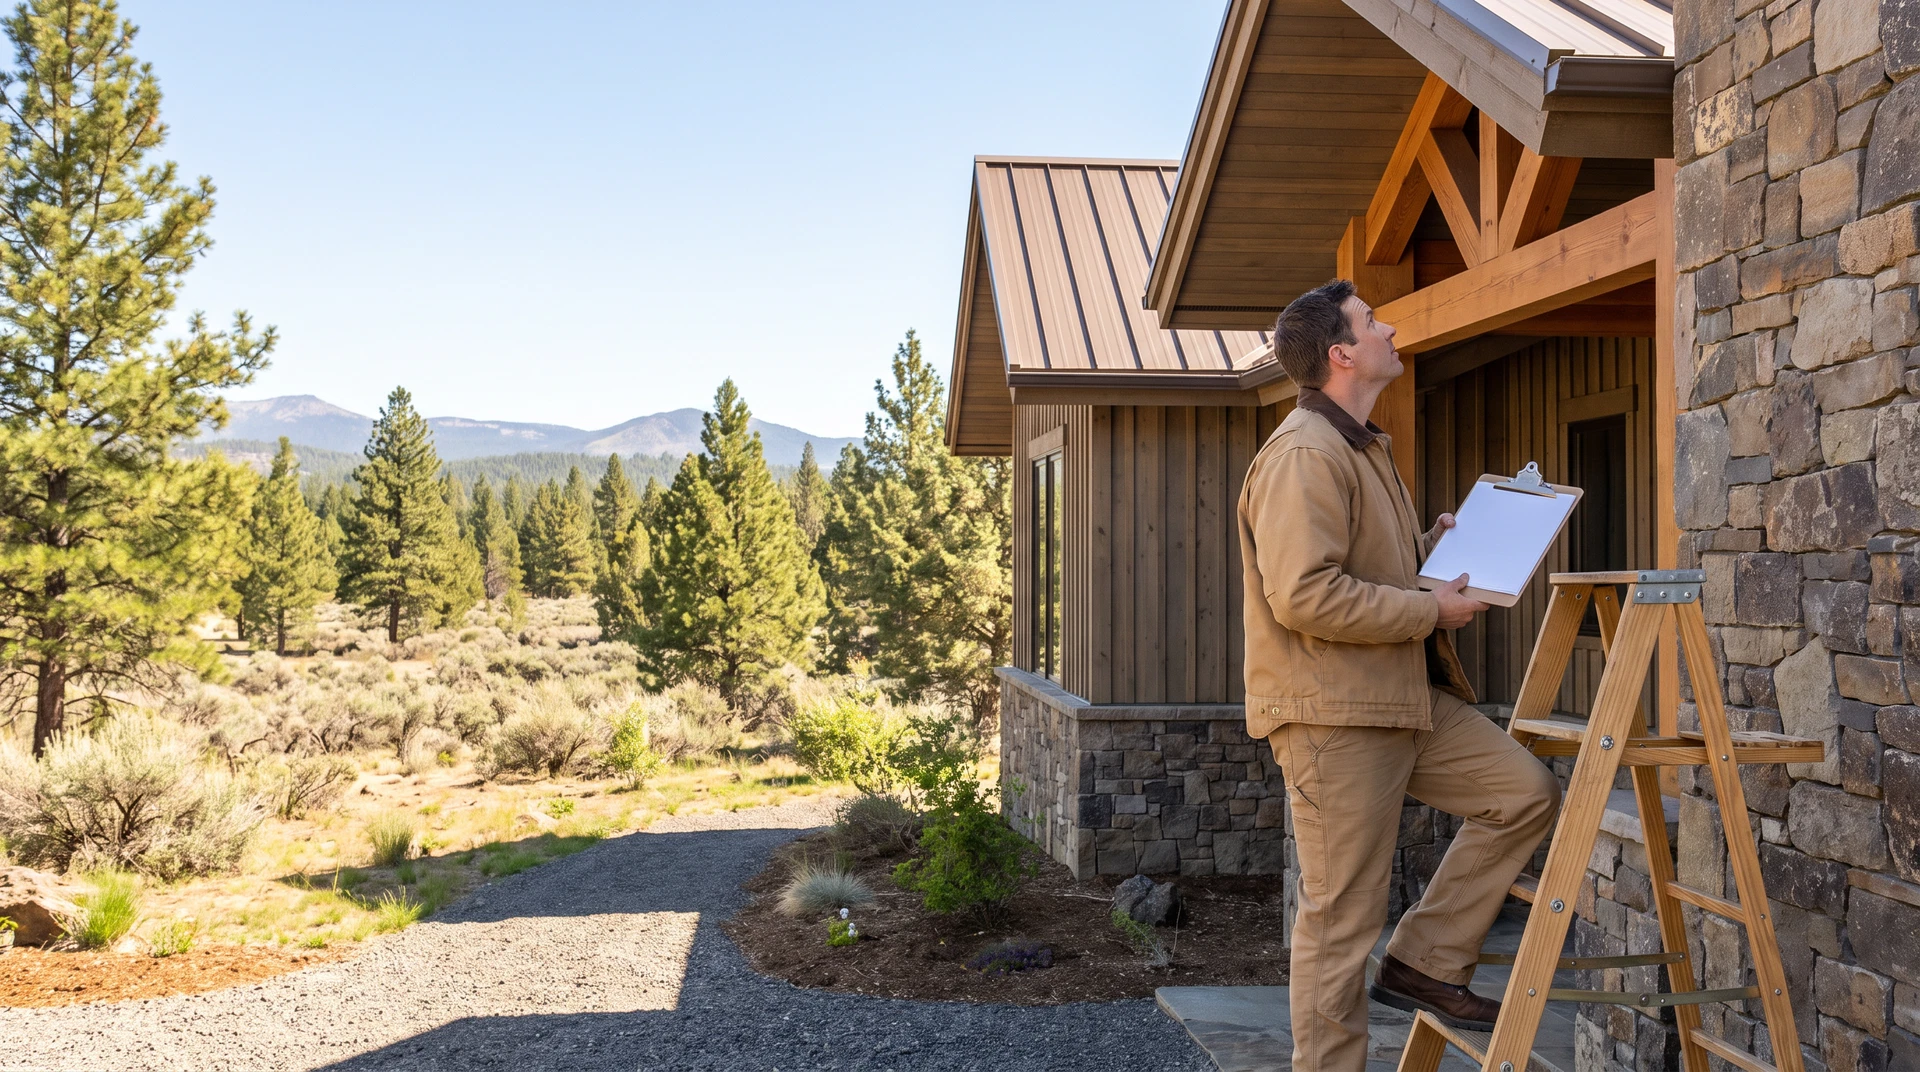
Coverage planning for Oregon residential and commercial property inspection professionals.
Home inspectors in Oregon may work across occupied homes, vacant properties, construction sites, roofs, crawlspaces, client appointments, and detailed reporting systems. A useful insurance review considers the inspection services offered, contracts, reports, equipment, travel, technology, subcontractors, and the conditions under which work is performed.
Prineville Insurance is an independent agency. We can help eligible inspection businesses compare available options, but policy availability, pricing, claim outcomes, and coverage depend on carrier underwriting and the actual terms, limits, exclusions, deductibles, and endorsements selected.
A practical review starts with the operation, current controls, and the terms of the selected policy.
Inspection reports, opinions, scope limitations, standards of practice, and client agreements can create professional-service questions that should be discussed with the selected policy.
Property visits, client meetings, and business operations can create third-party injury or property-damage questions that vary by work practices and policy terms.
Ladders, thermal tools, moisture meters, cameras, laptops, drones where applicable, and other equipment may need a value, transit, and storage conversation.
Travel between appointments, business-owned vehicles, employee use, and equipment transport can create separate coverage questions.
Reports, photos, client records, scheduling systems, and payment information can raise technology, privacy, and cyber-related questions.
Real-estate professionals, commercial clients, property managers, and other partners may request certificates or specific contractual terms before work begins.
An inspection agreement, stated scope, documentation practices, and record retention can affect the questions an insurer and the business should consider.
Property conditions, roofs, crawlspaces, occupied homes, utilities, and travel can vary substantially from one assignment to another.
Digital reports, photos, online delivery, and client records can make cyber hygiene and data practices relevant to risk-management discussions.
An independent agency can help eligible inspectors compare available options and understand the terms to review before selecting a policy.
Share the property types, inspection scope, report format, equipment, staff, contractors, travel, client contracts, and any specialty services performed.
Current declarations pages, report samples or scope descriptions, contracts, revenue, payroll, vehicle details, equipment values, locations, loss history, and cybersecurity practices can support the discussion.
Carrier availability and policy terms vary. Review professional-service definitions, exclusions, deductibles, conditions, limits, endorsements, and contract requirements before relying on coverage.
Common insurance-planning questions for Oregon businesses and professionals.
Still have questions? Our licensed agents are here to help.
Get A Free QuoteReady to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.