


Personal Insurance

You Work From Home in Bend — But Does Your Insurance Know That?

July 29, 20269 min readPersonal Insurance
Monica Elsom — Owner & Principal Agent, Prineville Insurance

Monica Elsom

Owner & Principal Agent, Prineville Insurance

monica@prinevilleins.com(541) 447-6372

Bend, Oregon has one of the highest remote work rates in the entire country. According to the City of Bend's 2025 State of the Economy report, remote workers now account for 28% of Bend's total workforce — nearly double the national average. It's one of the reasons people move here: you can work for a Portland tech firm, a San Francisco startup, or a New York media company while living five minutes from the Deschutes River Trail.

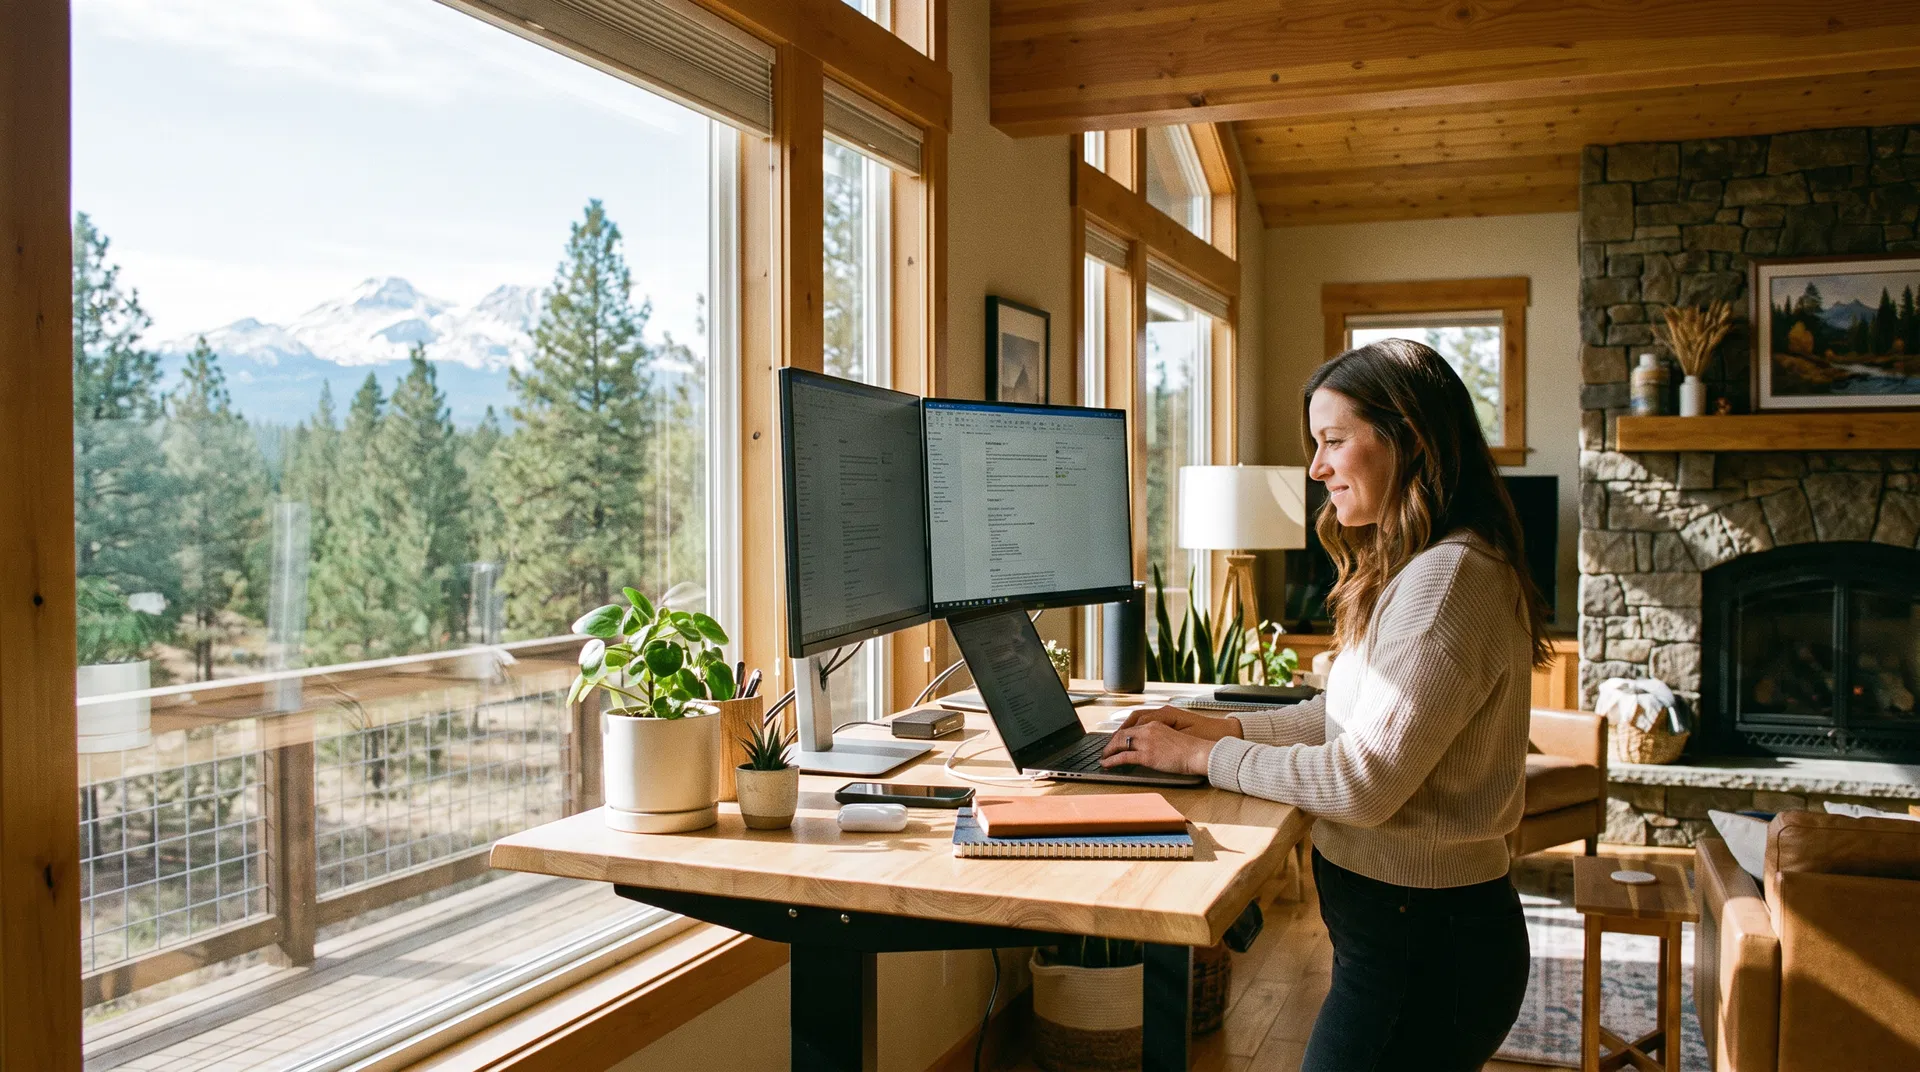
But here's the problem: most of those remote workers have never told their insurance company they work from home. And most don't realize that their standard homeowners or renters insurance policy has a hard cap of just $2,500 on business property — and provides zero liability coverage for anything business-related that happens in their home. That $4,000 standing desk, the dual-monitor setup, the professional camera gear, the NAS drive full of client files — most of it is either underinsured or completely unprotected.

Why Bend Is Ground Zero for This Problem

Remote work and Bend are practically synonymous. LinkedIn ranked Bend as the #1 small U.S. city for remote job postings, and the 2024 U.S. Census found that 24.8% of Bend workers work from home — compared to roughly 13% nationally. The city's population has grown by tens of thousands over the past decade, and a significant driver of that growth is people relocating specifically to work remotely from a place with better outdoor access and quality of life.

That influx means Central Oregon now has a large population of remote employees, freelancers, consultants, and independent contractors who have set up professional home offices — often with thousands of dollars in equipment — without ever updating their personal insurance to reflect how they actually use their home.

What Your Homeowners Policy Actually Covers (And Doesn't)

A standard homeowners insurance policy is designed to protect your home and your personal property. The moment something crosses the line from "personal" to "business," coverage gets complicated — and often disappears entirely.

The $2,500 Business Property Cap

Most standard homeowners policies include a sub-limit for business property — typically $2,500 for items kept at home and as low as $250 for items taken off-premises. That means if your home is burglarized and your work laptop, external monitors, and professional audio equipment are stolen, you may only recover $2,500 — even if the actual replacement cost is $8,000 or more.

For a remote worker with a modest setup, $2,500 might feel like enough. But consider what a fully equipped home office actually contains:

  • MacBook Pro or high-end Windows laptop: $1,500–$3,500
  • Dual external monitors: $600–$1,200
  • Ergonomic desk and chair: $800–$2,500
  • External hard drives, NAS, or RAID storage: $300–$1,500
  • Professional webcam, microphone, lighting: $400–$1,200
  • Printer, scanner, or specialty equipment: $200–$800

A mid-range home office setup easily totals $4,000–$8,000. A professional creative or developer setup can exceed $15,000. The $2,500 cap leaves a massive gap.

Zero Business Liability Coverage

The equipment gap is bad. The liability gap is potentially catastrophic. Standard homeowners policies explicitly exclude business liability — meaning if a client, vendor, or delivery person is injured at your home during a business-related visit, your homeowners policy will likely deny the claim.

Even if you never have clients come to your home, liability exposure exists. If you're a freelance consultant and a client claims your advice caused them financial harm, that's a professional liability claim — not covered by homeowners insurance. If you sell products from home and a customer is injured by something you made or sold, that's a product liability claim — also not covered.

No Business Interruption Coverage

If a fire, burst pipe, or other covered event damages your home and forces you to stop working for two weeks, your homeowners policy will cover the physical damage to your home. But it will not cover the income you lost while you couldn't work. For employees, this may be less critical — your employer may still pay you. But for freelancers, consultants, and independent contractors, two weeks without income can be financially devastating. Business interruption coverage fills that gap.


Does Your Policy Cover Your Home Office?

A quick policy review with a local agent can identify exactly where your coverage ends and what it would cost to fill the gaps — often for less than $200/year.

Employee vs. Freelancer: The Coverage Divide

Your coverage situation depends heavily on whether you're a remote employee or self-employed. The distinction matters enormously for insurance purposes.

Full-Time Remote Employees

If you work for a company as a W-2 employee and work from home, your employer's commercial insurance policies may extend some coverage to you while you're performing work duties. Specifically:

  • Employer-owned equipment (company laptop, company phone) is typically covered under the employer's commercial property policy.
  • Workers' compensation extends to remote workers — if you're injured while performing work tasks at home, you may have a workers' comp claim.
  • General liability for business-guest injuries may be covered under the employer's policy if a client visits your home for a work meeting.

However, your personal equipment used for work — your own laptop, your own monitors, your own desk — is not covered by your employer's policy. And the employer's coverage only applies during work hours and work activities. Your homeowners policy still has that $2,500 cap on business property.

Freelancers, Consultants, and Independent Contractors

If you're self-employed — whether you're a graphic designer, software developer, copywriter, photographer, financial consultant, or any other type of independent contractor — you have no employer coverage to fall back on. You are responsible for insuring your own equipment, your own liability, and your own income stream.

This is the group most at risk in Bend's remote work population. The city has attracted a significant number of location-independent professionals who left larger cities specifically to enjoy Central Oregon's lifestyle. Many of them are running what are effectively small businesses from their homes — and most are doing so with no business insurance whatsoever.

The Four Coverage Solutions for Bend Remote Workers

The good news: there are several ways to close the coverage gap, and most of them are surprisingly affordable. Here are the four main options, from simplest to most comprehensive.

1. Home Business Endorsement (Add-On to Your Homeowners Policy)

The simplest fix is adding a home business endorsement to your existing homeowners or renters insurance policy. This endorsement can increase your business property coverage from $2,500 to $10,000 or more, and may add limited business liability coverage. It's designed for low-risk home-based businesses and remote employees.

A home business endorsement typically costs $25–$75 per year — often less than the cost of a single month of your streaming subscriptions. It's the most cost-effective starting point for remote employees with modest equipment.

Limitations: endorsements don't cover professional liability (errors and omissions), don't cover business income loss, and may not be sufficient for freelancers with significant equipment or client-facing activities.

2. In-Home Business Policy

An in-home business policy is a standalone policy designed specifically for home-based businesses. It provides more comprehensive coverage than an endorsement, including:

  • Business property coverage up to $10,000–$25,000+
  • Business liability coverage for client injuries
  • Business income / loss of income coverage
  • Coverage for business property taken off-premises (to coffee shops, client sites, etc.)

An in-home business policy typically costs $250–$500 per year and is appropriate for freelancers, consultants, and independent contractors with moderate equipment and occasional client contact.

3. Business Owners Policy (BOP)

A Business Owners Policy (BOP) combines commercial property insurance and general liability insurance in a single package. It's designed for small businesses and provides the most comprehensive coverage for home-based professionals.

A BOP is appropriate if you have significant business equipment, meet with clients regularly, have employees (even part-time), or operate a business that generates meaningful revenue. BOPs typically cost $500–$1,500 per year depending on your industry and revenue, and can be bundled with commercial insurance for additional savings.

4. Professional Liability Insurance (Errors & Omissions)

If you provide professional advice, services, or expertise — as a consultant, designer, developer, writer, financial advisor, or any other knowledge worker — you should also consider professional liability insurance, also known as Errors & Omissions (E&O) insurance.

Professional liability covers claims that your work, advice, or services caused a client financial harm. It's not included in homeowners policies, home business endorsements, or standard BOPs. For consultants and freelancers, it's one of the most important coverages to have — and one of the most commonly overlooked.

What About Cyber Liability?

Remote workers handle sensitive data. Client files, financial records, personal information, proprietary business data — it all flows through your home network and your personal devices. If that data is compromised in a breach, ransomware attack, or accidental disclosure, you could face significant liability.

Standard homeowners policies provide no cyber liability coverage. Some in-home business policies include limited cyber coverage, but for remote workers handling sensitive client data, a standalone cyber liability policy is worth considering. Cyber liability insurance for small businesses and freelancers typically costs $500–$1,500 per year.

The Crook County and Central Oregon Context

Prineville and Crook County have their own growing remote work population. The same trends driving Bend's growth — lower cost of living relative to Portland and the Bay Area, outdoor lifestyle, and high quality of life — are drawing remote workers to Prineville, Redmond, Sisters, and Madras as well.

For homeowners in these communities, the insurance gap is the same. Whether you're working remotely from a home in Prineville's Ochoco Highlands or a Bend neighborhood near the Old Mill District, your standard homeowners policy has the same $2,500 business property cap and the same business liability exclusion.

The difference is that in smaller communities, the local insurance agent relationship matters more. At Prineville Insurance, we know Central Oregon — we know the specific risks, the local carriers, and the coverage options that make sense for remote workers in this region. We've helped clients in Prineville, Bend, Redmond, Sisters, Madras, and La Pine find the right coverage for their home offices.

Are You a Freelancer or Independent Contractor?

Freelancers and independent contractors have zero employer coverage to fall back on. A dedicated in-home business policy or BOP can protect your equipment, your income, and your professional reputation — often for less than $500/year.

A Quick Self-Assessment: Do You Have a Coverage Gap?

Answer these questions honestly. If you answer "yes" to any of them, you likely have a coverage gap worth addressing:

  • Do you have more than $2,500 worth of work-related equipment in your home?
  • Do you ever take your work laptop or equipment outside your home (to coffee shops, client sites, coworking spaces)?
  • Do you work as a freelancer, consultant, or independent contractor?
  • Do you ever have clients, vendors, or business associates visit your home?
  • Do you handle sensitive client data, financial information, or proprietary business information?
  • Would losing two weeks of income due to a home repair emergency cause significant financial hardship?
  • Have you never told your insurance company that you work from home?

If you answered yes to two or more of these questions, it's worth having a conversation with your insurance agent about your current coverage and what it would cost to fill the gaps.

How to Have the Conversation With Your Insurance Agent

Many remote workers avoid this conversation because they're afraid their premium will skyrocket. In reality, the cost of adding home office coverage is usually modest — and the conversation is straightforward.

Here's what to tell your agent:

  • "I work from home [full-time / part-time] as a [employee / freelancer / consultant]."
  • "I have approximately $X worth of work-related equipment in my home."
  • "I [do / do not] have clients or business associates visit my home."
  • "I [am / am not] self-employed or running a business from home."

With that information, your agent can review your current homeowners or renters policy, identify the specific gaps, and present options for filling them. The whole conversation typically takes 15–20 minutes and can save you from a five-figure loss.

Don't Wait for a Claim to Find Out You're Not Covered

The most common way people discover their home office isn't covered is when they file a claim — and it's denied. A laptop stolen in a burglary. A fire that destroys a home office. A client who slips on the front steps. These are the moments when the coverage gap becomes real, and by then it's too late to fix it.

The cost of a home business endorsement or in-home business policy is almost always less than the deductible on a single claim — let alone the full replacement cost of your equipment or the cost of defending a liability lawsuit. For most Bend remote workers, the right coverage costs less than $200 per year. For freelancers and independent contractors, a full BOP might cost $600–$800 per year.

Compared to the risk of losing $10,000 in equipment or facing a $50,000 liability claim with no coverage, that's a straightforward calculation.

Prineville Insurance: Central Oregon's Local Insurance Experts

Prineville Insurance has been serving Central Oregon families and businesses since 1935. We represent 50+ carriers, which means we can shop the market and find the right coverage for your specific situation — whether you're a remote employee in Bend, a freelance designer in Redmond, or a consultant working from a home office in Prineville.

We understand the Central Oregon lifestyle and the specific risks that come with it. We've helped hundreds of remote workers, freelancers, and home-based business owners find coverage that actually protects them — without overpaying for coverage they don't need.

If you work from home and haven't reviewed your insurance recently, now is a good time. A quick review with one of our local agents can tell you exactly where you stand — and what it would cost to make sure you're properly protected.

Learn more about our personal insurance options, commercial insurance for home-based businesses, and our independent agency approach that lets us compare options across dozens of carriers to find the best fit for you.

Get a Free Home Office Insurance Review

Tell us how you use your home for work, and we'll review your current coverage and show you exactly what it would cost to properly protect your home office — with no obligation.

Get in Touch

Ready to protect what matters most? Contact us today for a no-obligation insurance review. Our experienced agents are here to help you find the right coverage for your needs.

Sending your request…

Your message goes to the Prineville Insurance team. Privacy Policy
