



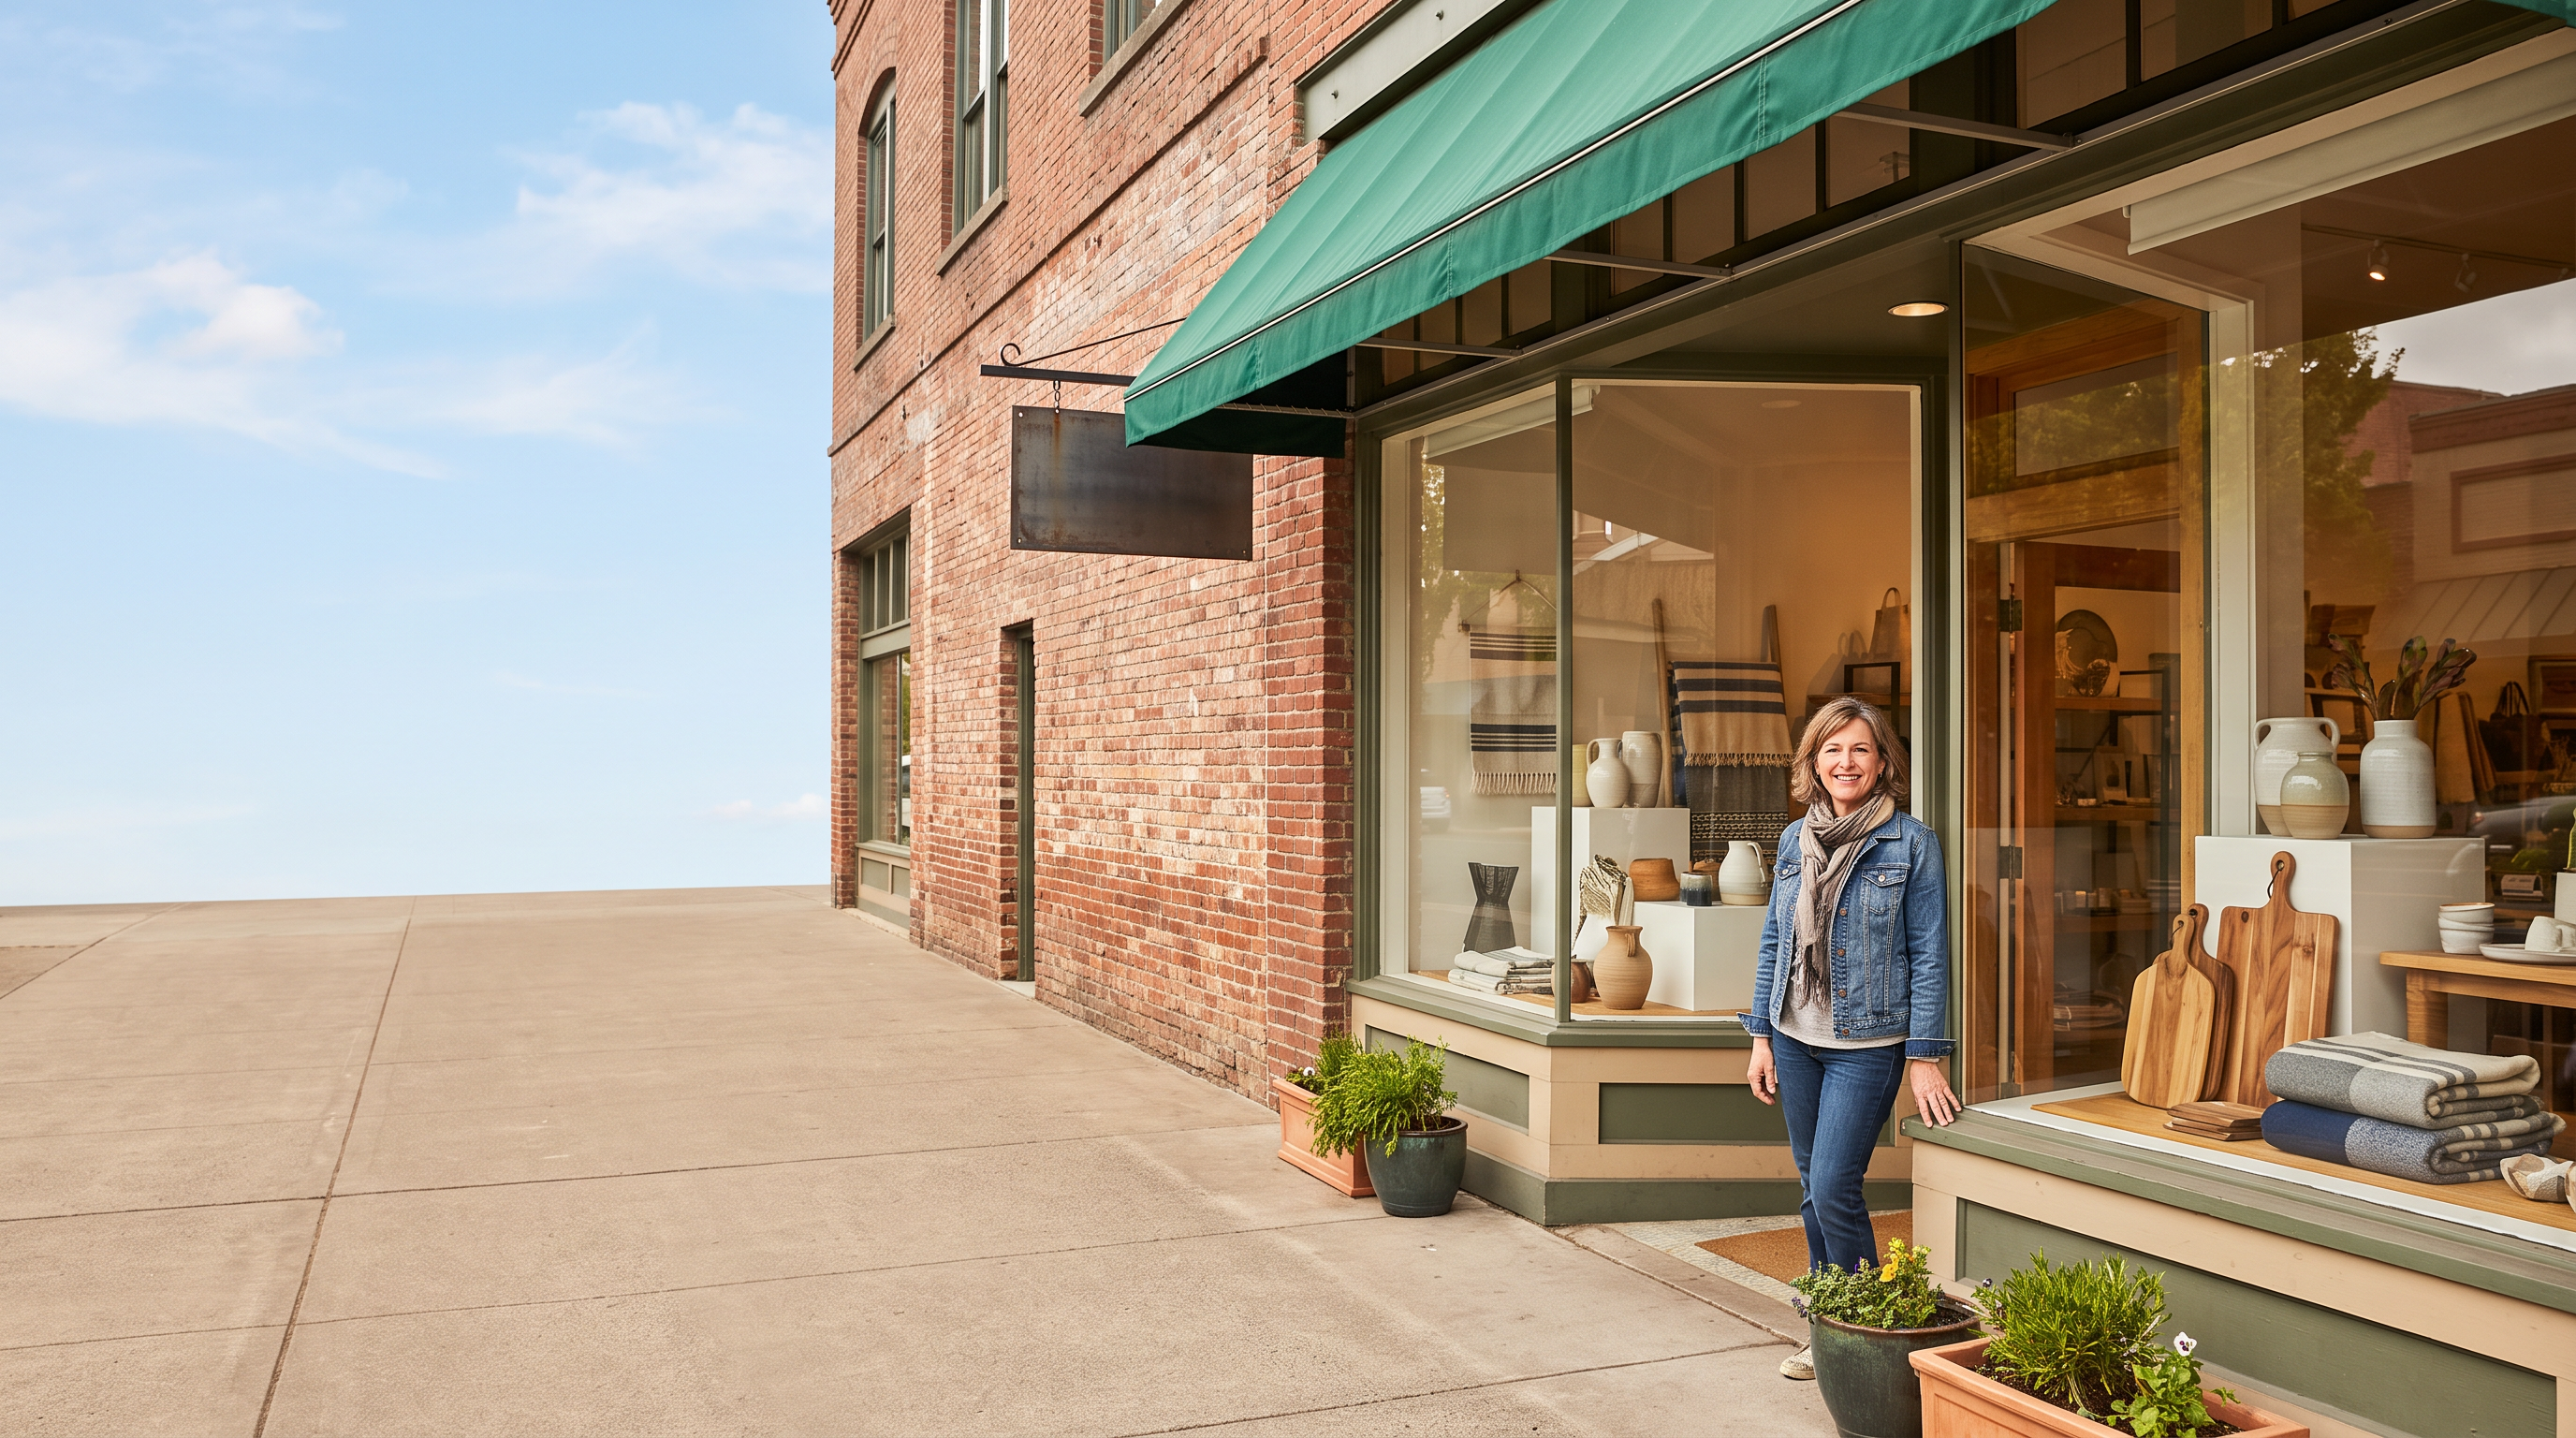

A Main Street retail storefront is where the public meets your business: the plate-glass windows, front door, awning, sign, merchandise display, entry mat, sidewalk, and checkout counter all work together. In Prineville, Bend, Redmond, Madras, Sisters, La Pine, and other Oregon communities, a small change to that storefront can create new questions about property, liability, a lease, permitting, and downtime. Start with a complete retail store insurance review rather than treating the building front as an afterthought.
This guide is educational information, not insurance, legal, construction, lease, accessibility, code, permitting, or claim advice. It does not establish who is responsible for a sidewalk, window, sign, awning, tenant improvement, injury, or closure; it does not guarantee coverage or compliance. The signed lease, local rules, ownership, maintenance arrangements, policy form, declarations, endorsements, exclusions, limits, deductibles, valuation, documented conditions, and facts of a loss all matter. Before you sign a lease, install signage, rebuild a window, alter the façade, or submit a claim, consult the appropriate landlord, property manager, municipality, contractor, legal adviser, and insurance professional.
Think Beyond the Four Walls: A Storefront Has Multiple Property Interests
Oregon’s Division of Financial Regulation (DFR) identifies a wide range of business property that can be owned or leased, including the building, inventory, furniture, equipment, computers, valuable papers, signs, fences, and outdoor property.[1] A downtown shop often has all of these in a small, visible footprint. The business may own the inventory and fixtures while a landlord owns the building shell; an awning may have been installed by a prior tenant; a projecting sign might sit over a public-facing walkway; and a custom display can blend permanently installed work with movable business property.
Make a storefront inventory before a renewal, move, or remodel. Photograph the exterior from multiple angles; record plate-glass dimensions, display fixtures, exterior lighting, awnings, signs, door hardware, point-of-sale equipment, security features, and any items installed under a tenant-improvement agreement. Match each item to its owner, maintenance party, replacement value, and the portion of the policy or contract you need to review. This is the practical foundation of a good commercial property insurance conversation.
| Storefront element | Question to organize | Record to keep current |
|---|---|---|
| Plate glass, doors, and displays | Is the item part of the building, a tenant improvement, or business personal property? What does the actual policy say about covered causes of loss, glass, vandalism, deductibles, vacancy, and valuation? | Dated façade photos, measurements, vendor invoices, lease language, alarm/camera details, and a temporary-boarding contact. |
| Signs, awnings, and exterior fixtures | Who owns, maintains, insures, and approves them? Which local permit, clearance, electrical, structural, or landlord conditions apply? | Permit/approval file, property-manager authorization, installation documents, maintenance records, and clear photos. |
| Sidewalk, entrance, and customer path | Who controls inspection, snow/ice or water response, mats, lighting, exterior furniture, deliveries, and repairs? | Inspection routine, incident log, work orders, photos, and vendor certificates if applicable. |
| Tenant improvements | Does the signed lease say who restores build-outs, counters, plumbing, HVAC, flooring, accessibility improvements, or storefront work after damage? | Lease exhibits, change orders, contractor documents, drawings, final invoices, and certificates requested by the landlord. |
| Retail inventory and records | Could the business replace seasonal stock, a window display, sales records, POS hardware, and customer-facing tools after a covered loss? | Current inventory, purchase cost, supplier contacts, backups, product photos, and financial records. |
Plate Glass Is More Than a Window: It Is Security, Merchandise, and Time
Storefront glass can put a business directly on the street, show merchandise after hours, and bring daylight into the sales floor. It can also be affected by impact, vandalism, burglary, wind, water, a damaged display, or a shutdown while replacement work is arranged. Do not assume the word “property” answers every question. Ask how the particular policy addresses the storefront as written: coverage trigger, specific property description, deductible, glass provisions, temporary protection, debris removal, ordinance or law, valuation, and whether a loss changes the ability to operate.
DFR explains the difference between actual-cash-value and replacement-cost approaches: actual cash value considers depreciation, while replacement cost concerns the cost to replace, rebuild, or repair with materials of similar kind and quality.[1] That broad distinction is a prompt for a policy review, not a coverage answer. A storefront may involve specialized safety glass, historic details, custom framing, display fixtures, and municipal or landlord requirements that change the restoration discussion. Keep dimensions, invoices, samples, and photographs before a loss rather than trying to rebuild the record afterward.
Signs, Awnings, and Sidewalks: Verify Local Rules Before You Install or Move Anything
Sign and awning projects are insurance questions, but they are also property, safety, and permitting questions. The City of Prineville’s sign ordinance says most sign work requires a permit, regulates signs near public rights-of-way, and includes requirements for projecting signs and awnings/canopies. It also states that a permit does not reduce the responsibility of persons involved for damage caused by a defect.[4] Prineville’s code gives a useful local example: it provides clearance standards for certain projecting signs and for awnings/canopies above sidewalks and vehicle access points. The specific current rule, zone, property line, historic considerations, and application requirements must be verified with the City—not inferred from this article.
Bend’s published sign guidance provides another Central Oregon example. It says most permanent signs typically require a permit and treats signs on buildings and awnings/canopies as permanent-sign categories. Its portable-sign guidance emphasizes keeping accessible routes, curb ramps, entrances, exits, fire escapes, transit-stop areas, and required pedestrian space clear.[5] Other communities can use different codes, permit processes, and maintenance standards. Before an A-frame, blade sign, banner, awning, outdoor display, or sidewalk fixture goes up, check local requirements, lease approval, insurance implications, and the safest way to preserve public access.
Bring the Lease and Storefront Details Into One Review
Prineville Insurance can help organize a policy-specific storefront conversation around plate glass, signs, awnings, sidewalk exposure, tenant improvements, inventory, customer safety, and business continuity.
Leased Retail Space: The Lease Is a Starting Point, Not a Coverage Determination
Retail tenants often focus on the monthly rent and the sales floor. The lease may also allocate responsibility for windows, doors, building glass, signs, awnings, common areas, snow or water removal, HVAC, plumbing, roof leaks, tenant improvements, restoration, indemnity, insurance limits, deductibles, certificates, additional-insured language, and notices after a loss. Those clauses need to be read together; an isolated certificate does not amend a policy or decide all contractual obligations.
Tenant improvements require the same care. Municipal guidance from Warrenton, Oregon notes that a change of use or occupancy can require a permit under the Oregon Structural Specialty Code framework even without structural work.[6] That does not mean every update is the same, or that a policy replaces permitting or landlord approval. Before a new storefront, counter, shelving system, accessible entrance feature, electrical sign, security system, or awning installation, create a shared file with the signed lease, landlord consent, municipal approval, drawings, contractor agreement, work order, photos, invoices, and the insurance specifications requested by the lease.
A retailer should ask the insurer to evaluate the actual business-personal-property and improvement description, while qualified legal and property professionals clarify the lease. If the store has significant assets or customer traffic, a separate umbrella liability insurance discussion may also be worthwhile. Availability, limits, underlying-policy requirements, exclusions, and fit vary by carrier and operation; an umbrella does not repair a gap created by an incorrect property description or an unreviewed contract.
Customer Safety Starts at the Door, but It Does Not End There
Oregon DFR explains that if someone is injured on business premises or by a product sold by the business, the business can be held responsible; it identifies commercial general liability as a key small-business coverage concern.[2] DFR also notes important areas standard liability insurance does not cover, including employee injury, auto claims, and certain employment-practices claims. The practical takeaway is not that a particular customer injury will be covered, but that storefront owners and tenants should identify exposures before an event and match them to the correct insurance and operations conversation.
Document an inspection routine for the route a customer actually takes: parking or curb edge, sidewalk, exterior lighting, awning drainage, mats, entry threshold, door hardware, display stands, electrical cords, checkout area, restrooms, and exit path. Train staff to identify water, ice, broken glass, unstable shelves, blocked paths, falling display risks, and compromised lighting. When an incident happens, prioritize people and emergency directions, then preserve accurate photographs, time-stamped observations, witness information, video retention, maintenance records, and the names of contractors or property contacts. For more detailed premises and product exposure questions, review general liability insurance as part of the wider program.
When the Doors Close: Plan for More Than the Repair Invoice
A boarded storefront can interrupt sales before a replacement pane arrives. A fire, theft, water loss, smoke event, wind event, or other covered property loss can also affect payroll, rent, utilities, seasonal inventory, supplier relationships, online fulfillment, customer communication, and the ability to reopen on the same schedule. Oregon DFR says business interruption/continuation coverage can address fixed costs and profits that would have been earned when a covered event causes an extended shutdown.[3] It is not a blanket promise for every decline in sales, closure, event, or foot-traffic problem.
Keep current financial records, inventory reports, daily sales history, payroll, lease obligations, supplier contacts, restoration invoices, and an alternate-sales plan. Consider what could continue through online orders, curbside pickup, a temporary location, a pop-up, or delivery—and what extra costs that plan could create. Then review your business interruption insurance wording alongside property coverage, not after a loss. A Central Oregon storefront should also include smoke, wildfire conditions, road access, and customer communication in its continuity plan; the site’s wildfire insurance resource is a useful starting point for broader local preparedness questions.
Retail Records, Theft, Employees, and Data Need Their Own Conversations
A Main Street shop can hold cash, gift cards, inventory, displays, vendor consignment items, keys, security credentials, point-of-sale hardware, email accounts, loyalty information, and staff schedules. Each may point to a different policy or process. Theft or employee dishonesty questions may belong in a crime insurance discussion. A data breach, checkout-system disruption, fraudulent payment request, or customer-information incident may require a separate cyber liability insurance review. Do not assume a basic property or liability policy responds to every financial or data loss.
Employee responsibilities also deserve written clarity. Opening and closing the store, carrying cash, moving displays, handling deliveries, cleaning spills, inspecting the entrance, documenting incidents, and responding to a break-in can all involve workplace risks. Review payroll, duties, staffing, contractors, and loss-prevention practices alongside workers’ compensation coverage. Classification and coverage determinations depend on facts and applicable rules; a blog cannot make either determination.
A Practical Storefront Review Before Your Next Renewal or Remodel
Gather the signed lease and all amendments; a current certificate request list; property and improvement schedule; photographs of the façade, windows, signs, awnings, sidewalk, and entry; inventory and seasonal merchandise list; exterior and interior maintenance records; security and alarm details; copies of permits or approvals; contractor and vendor contacts; customer-incident procedures; financial records; sales-continuity plan; and loss history. Then compare the documents with the actual storefront your customers see every day.
A local review is especially helpful when a shop moves from Prineville to Bend, adds a second location in Redmond, remodels a historic storefront, changes the merchandise mix, begins selling online, brings in consigned merchandise, starts hosting events, or takes on a longer lease. You can also compare this article with the site’s broader Oregon retail store insurance guide before your conversation. The goal is not to make a coverage assumption—it is to make the insurance description, lease documents, property records, and operational plan agree before the next loss or renovation.
Frequently Asked Questions
Does a commercial property policy automatically cover a broken storefront window or plate glass?
Do not assume it does. A claim can turn on the policy form, covered cause of loss, property description, whether glass is part of the building or tenant’s interest, any glass or vandalism provisions, deductible, vacancy language, exclusions, valuation method, and the facts of the event. Ask for a policy-specific explanation before a loss, especially if the store has large display windows or custom glass.
Who insures an awning, sign, or tenant improvement in a leased retail space?
A lease, the owner’s policy, the tenant’s policy, endorsement wording, ownership, and the improvement agreement may all matter. Neither a lease clause nor a certificate of insurance alone tells the whole coverage story. Review the signed lease and work order with qualified legal, property-management, construction, and insurance professionals before installing or replacing an improvement.
If a customer slips outside a store, is the tenant always responsible?
No. Responsibility can depend on the lease, common-area and sidewalk arrangements, control of the area, the event, notice, maintenance records, municipal rules, and other facts. Commercial general liability is an important conversation for visitor injury exposures, but it does not decide fault or guarantee that a particular claim is covered.
Will business income insurance pay if a store closes for any reason?
No. Oregon DFR explains that business interruption/continuation insurance addresses fixed costs and lost profit when a covered event shuts down the business for an extended period. The actual policy controls: a covered cause of loss, waiting period, restoration period, limits, exclusions, extra-expense wording, financial records, and other conditions can affect whether and how a claim is evaluated.
Can I put a sidewalk sign or hanging sign anywhere outside my store?
Not safely or automatically. Local rules differ. For example, Prineville and Bend each regulate signs, while Bend’s published guidance addresses permits and keeping portable signs clear of accessible routes, curb ramps, entrances/exits, fire escapes, and other pedestrian areas. Verify current rules, landlord approval, any historic or district restrictions, permit needs, clearances, and property boundaries with the applicable jurisdiction before installation or use.
Put the Storefront, Lease, and Continuity Plan in One Conversation
Your storefront is part of the customer experience and part of the risk profile. A change to the glass, sign, awning, sidewalk, lease, floor plan, merchandise, employee roster, online sales, or storefront address is a good reason to update the insurance conversation rather than wait for an incident. Bring the real documents and the real photos—the details make the review more useful.
Prineville Insurance can help Central Oregon retailers organize a policy-specific review around commercial property, customer injury exposures, business income, employees, theft, cyber, leases, and storefront improvements. Bring your lease, certificate requirements, inventory, property records, vendor agreements, improvement documents, and current policies so the discussion reflects the business you actually operate.
References
- Oregon Division of Financial Regulation — Property Insurance
- Oregon Division of Financial Regulation — Liability Insurance
- Oregon Division of Financial Regulation — Business Interruption Insurance
- City of Prineville — Chapter 152 Sign Ordinance
- City of Bend — Signs
- City of Warrenton — Commercial Tenant Improvement


